He built an ambulance company out of his mother’s garage. Now his Sydney lender is betting that a bank’s rejection, once a verdict on a borrower’s standing, is mostly a paperwork problem. The cycle may have something to say about that.
There is a particular silence that settles over a business owner when the bank says no. It usually arrives by email, weeks after the tax returns and the accountant’s careful cover letter disappeared into an institution that does not explain itself. For a generation of Australian owners, that silence carried weight. A bank’s decline was a verdict on the borrower’s standing, handed down by the only court in town that mattered.
Hadley Shapiro does not think the verdict means what it used to. He thinks it is mostly a formatting error.
“I spent sixteen years in a business where response time was measured in minutes,” Shapiro says. “An eight-week credit queue was never going to make sense to me. The bank is not assessing the business. It is assessing whether the paperwork fits the template.”
He arrived at that view by an unusual road. Before he was a lender, he ran ambulances. He started Medi Response from his mother’s garage at 19 and spent the next 16 years building it into an emergency services group operating across seven countries, with hundreds of staff and the compliance machinery that keeping people alive demands. When he moved into private capital advisory in Sydney, he assumed the hard operational problems were behind him. What he found instead was a procession of asset-rich, profitable owners being shown the door because their affairs did not fit a product box.
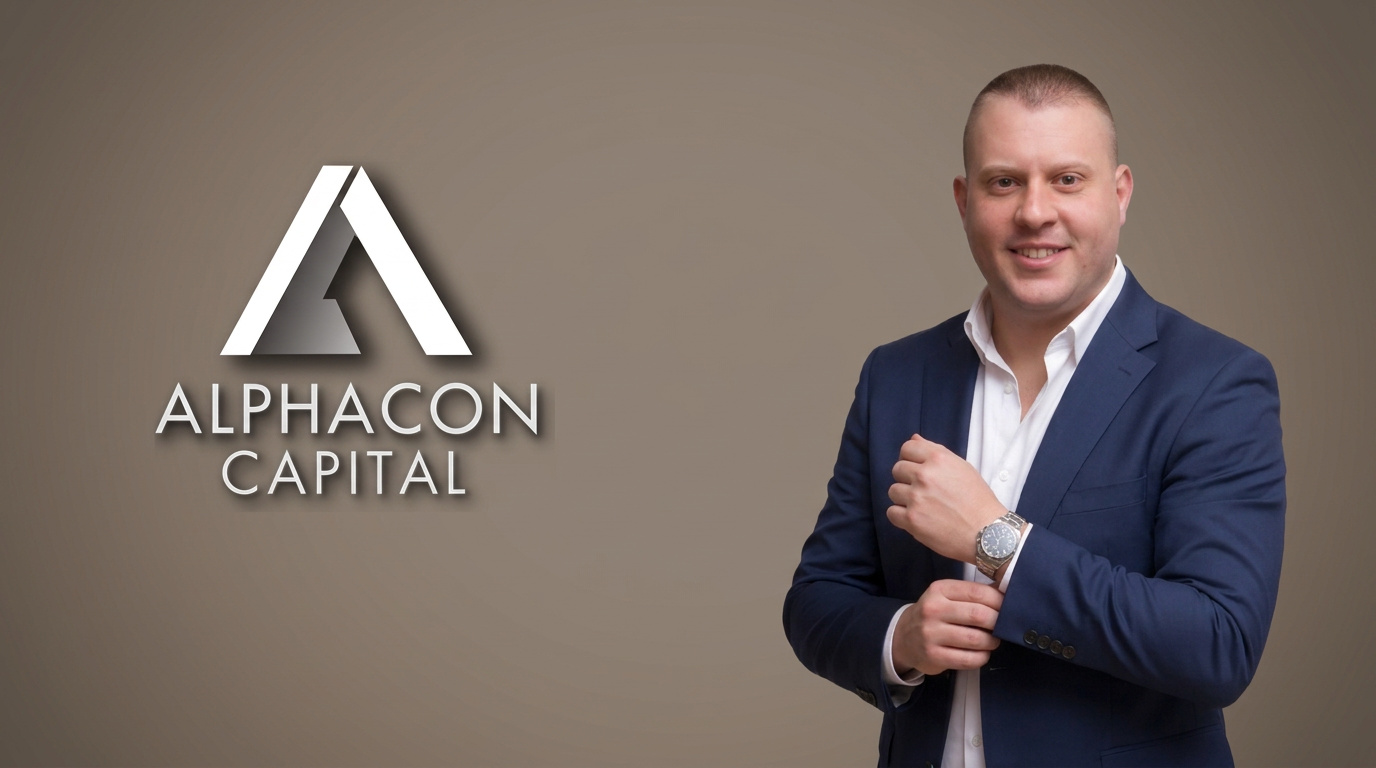
The company’s publicity portrait has him with his arms folded, in a navy blazer and a white shirt open at the collar. There is no tie, which in Sydney finance is its own small statement.
The bank’s no is losing its authority
The timing of his bet is pointed. The Reserve Bank of Australia lifted the cash rate to 4.60 percent on September 29, its fourth increase of 2026. Australia had 2,814,778 actively trading businesses at June 30, according to the Australian Bureau of Statistics, and companies showed the largest net growth of any legal structure, up 5.2 percent in a year to 1.27 million. Credit from non-bank lenders has been growing faster than bank credit, the RBA noted in its March Financial Stability Review. The money, in other words, has started to go where the verdicts are kinder.
Alphacon Capital, the Sydney lender Shapiro founded, is a wager on that drift. The cases behind his conviction were unglamorous. A manufacturer with a paid-down factory could not raise working capital against it in time to take a supplier’s offer. A developer with finished stock sat out a committee cycle while a purchaser’s finance clause expired. A family company run by an investor with two decades of form failed a serviceability calculation written for someone on a salary. Each time the asset was real and the plan was sound. Each time the system said no anyway.
Alphacon writes business-purpose loans to companies and corporate trustees, secured against Australian property, with indicative terms inside 24 hours and settlement measured in weeks. It assesses the security and the borrower’s plan, and pays little attention to the shape of a payslip. Shapiro traces the habit straight back to the ambulance years.
“Running emergency services teaches you that speed and discipline are not opposites. The fastest response in the world is worthless if it is the wrong response. We built the credit process the same way. Fast, but never casual.”
Manners count for a great deal in private credit
Every loan is secured by a registered mortgage over real property. The exit, whether a refinance to a mainstream lender or a sale, is settled on before any money moves, so nobody discovers it later. The firm lends to companies for business purposes only, which keeps it among professionally advised borrowers.
Business arrives two ways. A national broker network sends scenarios daily, drawn by the speed of an answer, and a direct channel serves owners who find the firm themselves. Shapiro is particular about the first. On a deal a broker introduces, Alphacon does not market to the client. Lenders in this corner of finance have not always kept that promise, so the restraint passes for exquisite manners.
The rest of his code runs mostly to refusals. He writes no consumer loans and no home loans, and he will not sell a product that works only if the borrower misunderstands what they signed. Pricing is disclosed before commitment, which in parts of this market is a novelty.
“The worst version of this industry makes money when the client loses. We built the opposite. If our borrower’s plan works, they refinance out, the broker looks good, and everyone does the next deal together. Alignment is not a slogan. It is the business model.”
The cycle is about to audit everyone
It is a handsome philosophy, and handsome philosophies tend to be tested at inconvenient moments. The Australian Securities and Investments Commission warned in June that private credit faces its first real test, citing tighter liquidity, emerging borrower stress and early signs of credit deterioration. The collateral is losing value too. Cotality’s national Home Value Index fell 1.1 percent in September, the sixth straight monthly decline, leaving dwelling values 5.2 percent below their March peak; Sydney is down 8.6 percent from its February high. A lender that sizes its loans on the property is exposed to exactly that slide. And a 24-hour answer is a far easier promise to keep at modest volume than at ten times the deal flow. Plenty of lenders have sounded principled on the way up.
Shapiro does not pretend otherwise. His ambition, he says, is a book whose loans still look sensible three years after they were written, which is a more interesting boast than size. Trust comes first in this business and growth follows it, in his telling. Brokers send their next file to whoever handled the last one well, and borrowers return when the exit they were promised is the exit they got.
What he is selling, in the end, is a second opinion, from a man who once measured service in minutes, on owners the old court had already judged.
“Banks lend on what you declare. We lend on what you have built,” he says. “There is a generation of owners who have done everything right and still cannot get served. That is not a niche. That is a structural gap, and we intend to fill it properly.”